

In our experience placing roofing contractors nationwide, including in Montana, general liability insurance for a small roofing company of one or two people usually comes in around $1,000 to $1,500 for the year, and general liability with workers’ compensation for a larger roofing business usually comes in around $2,500 to $3,800 for the year. A Montana roofer’s own quote can land inside or outside those ranges, and the drivers below are what move it.
A Montana roofer will not find a posted price for roofing contractor insurance, and winter load and fire shape the exposure, not plains hail. Heavy snow, repeated freeze-thaw and ice-dam cycles, and wildfire embers in wildland-urban-interface areas shape roof risk, while chinook downslope winds sweep the Rocky Mountain front. A roofer’s cost is derived from that company’s own record and the roofs it has left standing, not from a chart.
That answer frustrates owners who want an exact number, but it is the honest one, and the Montana drivers are specific enough that understanding them is worth far more than any average. A residential re-roof crew in Bozeman and a commercial low-slope operation in Billings are the same trade only in name. Below is what moves the number, starting with the climate that defines Montana roofing.
Snow load and wildfire embers, not hail, define Montana roofs
Montana’s roof risk is a Mountain-West story. Heavy snow loads and repeated freeze-thaw and ice-dam cycling stress roofs through long winters, forested counties carry genuine wildfire-ember exposure at the wildland-urban interface, and chinook downslope winds add a sharp wind element along the front. For a roofing contractor these perils shape cost through the roofs you install and the loss record a carrier reads — snow-load failures and ember-driven damage are the claims that matter here, not hail. Both demand swings after hard seasons and your claims history carry weight. For the full market and regulatory picture, see our Montana roofing contractor insurance page — that page is the overview, and this one is the cost explainer that companions it. The market is overseen by the Montana Commissioner of Securities and Insurance.
Why there is no fixed price
A premium is the output of an underwriting model, not a sticker. The carrier takes your specific exposures — how many people you employ and what they do on the roof, the revenue behind your completed work, your loss history, and the limits your contracts require — and prices each line against them. Change any input and the number moves. A statewide average is misleading because a mountain residential re-roofer and a valley commercial contractor carry genuinely different pictures. For a roofing contractor the cost is built mostly from two things: the crew working at height, and the roofs it leaves behind through hard winters.
Contractor registration and the workers-comp proof it demands
Montana does not license roofing as a trade skill, but it does require registration — and that registration has a cost-relevant hook. Contractors performing roofing must register with the Department of Labor and Industry as a construction contractor if they have employees, or as an independent contractor, and proof of a valid Montana workers compensation policy is required for that registration. There is no exam or trade classification, and local permits may still apply. Because comp is baked into the registration itself, a carrier reads your operation as one where the largest roofing line is already in force, and keeping it current is part of presenting an insurable business rather than a line item on a rate.
Crew payroll and the work at height
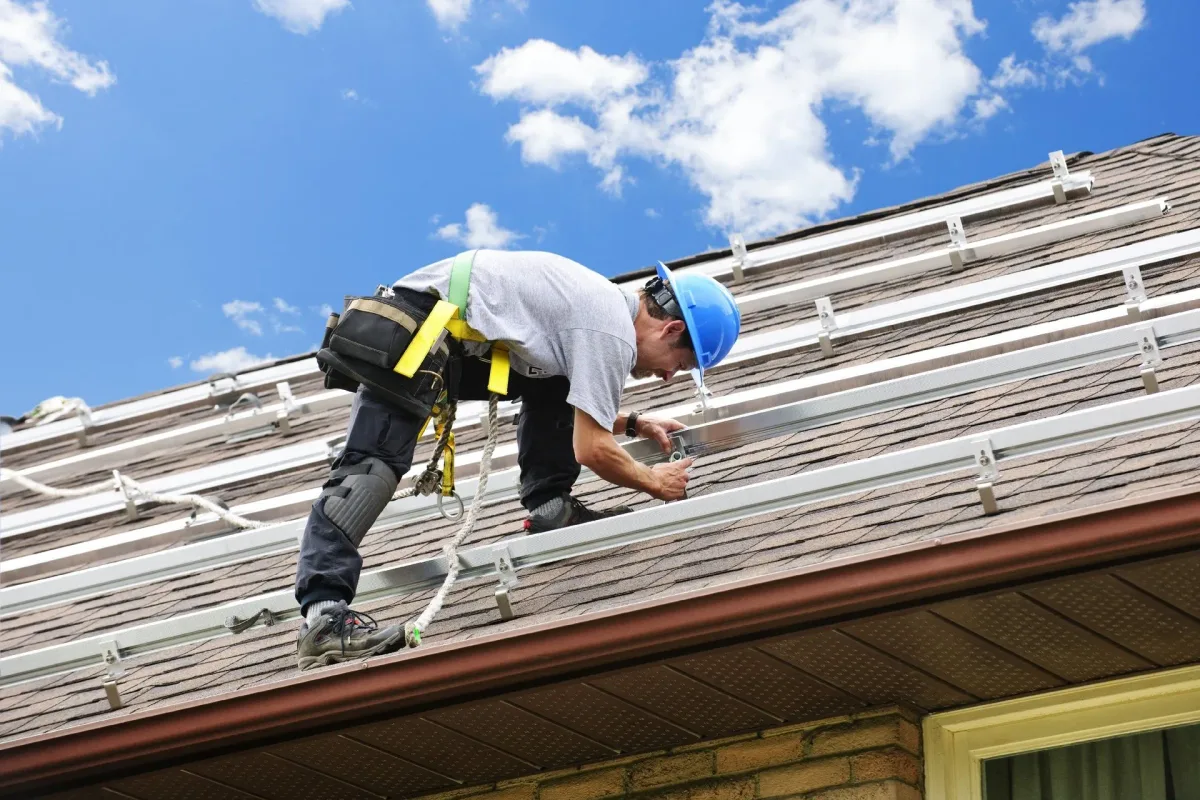
Payroll sets the cost of workers compensation and feeds general liability pricing, so for a roofing contractor it is a main input. In Montana the stakes extend further, since contractor registration calls for proof of a valid workers-comp policy. The work behind the dollars matters: roofing crews work up high, and a crew member’s fall is a workers compensation claim, the loss this coverage exists to pay. The Occupational Safety and Health Administration addresses roofing work by name in its fall-protection rule, and on snow-covered, icy roofs, where footing is a genuine hazard, we read your crew’s practices alongside its headcount.
The roof you leave behind in freeze-thaw country
Your revenue is a rating basis for general liability, but for a roofing contractor the exposure that defines the class is completed operations — the work you leave behind. A roof keeps existing after your crew is gone, and in Montana that installed roof is judged against heavy snow load, freeze-thaw, and ice dams for years. A roof that leaks or fails downstream can become a serious third-party property-damage or injury claim long after the job closes, and the completed-operations side of general liability is the signature line built to answer for it. Because a Montana roof carries such a long, winter-tested tail, your revenue and your workmanship-and-inspection record are inputs a carrier weighs closely. This is the roofing contractor’s defining cost driver.
Real-World Scenario: A Bozeman residential crew works through a heavy snow-load winter, its trucks and payroll surging with spring ice-dam repair and re-roof demand, while a Billings commercial contractor runs low-slope work on larger flat-roof projects that must carry snow weight for years. Both leave finished roofs that must shed load and resist ice dams, but an underwriter reads them differently — the residential crew’s exposure rides fall risk across many pitched roofs and storm-driven volume, the commercial contractor’s on fewer, larger low-slope jobs and higher contract limits. Same Montana, same roofing class — but the work mix and the completed-work picture price differently. The owner who can describe that picture clearly gets a sharper quote.
Work type, slope, and the hot-work share
The kind of roofing you do moves the number as much as how much you do, and in Montana the snow load and the wildfire interface both push toward systems built to carry weight and resist embers. A residential steep-slope crew carries a fall-and-completed-operations profile driven by shingle and pitched work at height and by the storm-and-repair volume that follows a hard season. A commercial and industrial low-slope operation carries a different signature: torch-down and hot-work application concentrates a genuine fire exposure during the job itself, separate from the completed-operations tail that follows it, and larger contracts pull in additional-insured obligations and higher limit requirements. A specialty metal and tile installer carries high material values and install-precision risk. Same trade, three genuinely different cost conversations — which is why a carrier wants to know your work mix before it prices anything. Standing-seam metal sheds heavy snow and resists ember ignition, an advantage in the wildland-urban interface, while the low-slope torch-down share carries the hot-work fire exposure during the job. Telling a carrier honestly how much of your revenue is torch-down versus mechanically fastened, and how much is steep-slope versus flat, is part of an accurate quote rather than a guess an underwriter has to make for you.
Trucks, tools, and staged materials
Beyond the crew and the completed work, a carrier prices what you drive and what you own. Commercial auto covers the trucks and trailers hauling crews, tear-off debris, and materials across long mountain distances, and it grows with the size of your rolling stock. Contractors’ equipment — inland marine — covers the tools, harnesses and fall-protection gear, standing-seam and metal-forming machines used by specialty metal and tile installers, and the materials you stage on the jobsite and in transit through winter. For a roofing contractor these are real but usually secondary to the crew and the completed-operations tail, and they are drivers you control by scheduling your trucks and equipment to their real value rather than guessing.
Getting an accurate Montana quote
Pricing starts from an honest account of your operation, including the paperwork around it. A broker needs your crew payroll along with the kind of work it reflects, your revenue and the kinds of roofs you leave in place, your contractor registration and workers-comp standing, how work divides between residential and commercial, truck and equipment values, how your claims ran through past winters, and the limits written into your contracts, including any umbrella that bigger contracts could require. We take those facts to roofing-class carriers. Our coverage overview shows how each line fits. When you are ready, request a quote and describe how your crews work, or visit our Montana roofing contractor insurance page, which sets out the market behind these drivers. What you end up paying will reflect your business alone.