

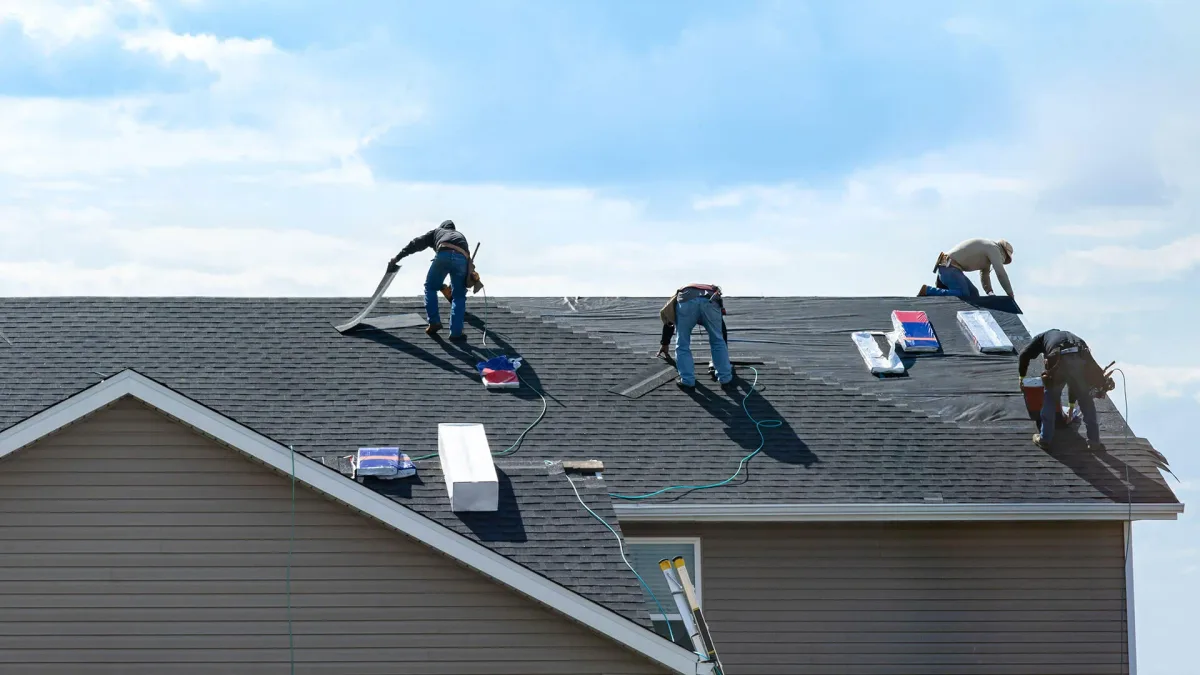
In our experience placing roofing contractors nationwide, including in Mississippi, general liability insurance for a small roofing company of one or two people usually comes in around $1,000 to $1,500 for the year, and general liability with workers’ compensation for a larger roofing business usually comes in around $2,500 to $3,800 for the year. A Mississippi roofer’s own quote can land inside or outside those ranges, and the drivers below are what move it.
There is no fixed price for roofing contractor insurance in Mississippi, and the Gulf-Coast wind pool is a good reminder of why. Coastal counties face hurricane and tropical wind and salt severe enough that the state created its own wind pool of last resort, while inland Mississippi sits in the Dixie Alley tornado and hail corridor. A carrier builds a roofing operation’s cost from its own storm record and the roofs it leaves behind — never from a rate card.
That answer frustrates owners who want an exact number, but it is the honest one, and the Mississippi drivers are specific enough that understanding them is worth far more than any average. A coastal re-roof crew in Gulfport and an interior operation in Jackson are the same trade only in name. Below is what moves the number, starting with the wind that frames the whole conversation.
The Gulf wind pool frames the Mississippi cost conversation
Mississippi’s roofing risk splits geographically. On the coast, hurricane and tropical wind and salt corrosion dominate, and the state-created Mississippi Windstorm Underwriting Association stands as the coastal wind pool of last resort — a state entity, not a private carrier — which tells you how stressed the wind-exposed property market is there. Inland, the Dixie Alley tornado and hail corridor drives the loss picture. For a roofing contractor both shape cost the same way: through demand swings after storms and through your loss record on the roofs you install. For the full market and regulatory picture, see our Mississippi roofing contractor insurance page — that page is the overview, and this one is the cost explainer that companions it. The market is overseen by the Mississippi Insurance Department.
Why there is no fixed price
Mississippi’s roofing market splits in two, and the split drives how a premium gets built. Along the Gulf Coast, around Gulfport and Biloxi, hurricane wind and salt dominate; inland, around Jackson, Hattiesburg and Southaven, the Dixie Alley tornado and hail corridor takes over. Your exposures turn into a price line by line: your crew and its work on the roof, the revenue tied to finished work, your claims record, and the limits your contracts impose. Move one input and the result moves with it. A statewide average hides that, since a coastal re-roofer and an inland commercial roofer present very different risks. Coastal wind exposure is backed by the state-created Mississippi Windstorm Underwriting Association, a pool of last resort. Showing wind-rated workmanship and a disciplined loss record gives a clean, well-documented submission real value in that setting.
The State Board of Contractors roofer license
Mississippi is a state that actually licenses roofing. The Mississippi State Board of Contractors offers a dedicated Residential Roofer license alongside its commercial license for work above the commercial threshold, with a state law and business-management exam required. A carrier reads that licensed operation as a real business, and the license you hold signals the work you do. A residential-only roofer and a commercial operation carry different exposures, so matching your license to your actual work mix is part of presenting an accurate picture rather than a line item on a rate.
Crew payroll and the work at height
A roofing contractor’s payroll forms the base for workers compensation and feeds general liability, so it shapes the price. The raw total is only half of it; the tasks being paid for matter as well. Crews work up high, and a fall is a workers compensation claim, the claim this line exists for. The Occupational Safety and Health Administration puts fall protection at the core of roofing safety for that reason. Along the coast, storm demand can fill crews quickly, so tell us about your fall-protection practice alongside your wages.
The completed-operations tail on the wind coast
Your revenue is a rating basis for general liability, but for a roofing contractor the exposure that defines the class is completed operations — the work you leave behind. A roof keeps existing after your crew is gone, and in Mississippi that installed roof is judged against the next hurricane on the coast and tornado wind inland. A roof that leaks or fails downstream can become a serious third-party property-damage or injury claim long after the job closes, and the completed-operations side of general liability is the signature line built to answer for it. Because a wind-rated Mississippi roof carries such a long tail, your revenue and your workmanship-and-inspection record are inputs a carrier weighs closely. This is the roofing contractor’s defining cost driver.
Real-World Scenario: A Gulfport coastal crew re-roofs storm-battered homes after a hurricane season, its trucks and payroll surging through the coastal repair rush, while a Jackson interior contractor runs residential steep-slope and some commercial low-slope work through the Dixie Alley storm season. Both leave finished roofs that must survive the next big wind, but an underwriter reads them differently — the coastal crew’s roofs are judged against hurricane wind and salt, the inland crew’s against tornado and hail, and the fall-and-completed-operations profiles diverge with the work mix. Same Mississippi, same roofing class — but the climate and the completed-work picture price differently. The owner who can describe that picture clearly gets a sharper quote.
Work type, slope, and the hot-work share
Work mix moves the price along with volume, and in Mississippi wind-rated detailing on the coast can separate a roof that comes through a hurricane from one that fails. Three profiles show the range. A steep-slope residential crew takes on fall and completed-operations exposure from shingle and pitched work, plus the repair surge that follows a rough storm season. A low-slope commercial and industrial operation looks different: torch-down and other hot-work application brings real fire exposure during the job, apart from the completed-operations tail afterward, and bigger contracts add additional-insured requirements and higher limits. A specialty metal and tile installer handles costly materials and a high bar for installation precision. One trade, three separate pricing conversations, so we ask for your mix before quoting. Coastal wind uplift bears on metal and mechanically fastened systems, while torch-down adds a fire hazard that wind does not. Be straight about the share of revenue in torch-down against mechanically fastened, and in steep against flat; that candor is part of getting a real quote, and it spares us from guessing for you.
Trucks, tools, and staged materials
Vehicles and owned equipment are priced too. Commercial auto responds to trucks and trailers that carry crews, tear-off debris, and materials, with cost rising alongside fleet size. Contractors’ equipment, written as inland marine, protects tools, harnesses, fall-protection equipment, standing-seam panel gear, metal-forming machines, and materials staged on a jobsite or in transit. These sit apart from the crew and the completed-operations tail, yet you control them: list trucks and equipment at real value instead of guessing at a figure that sounds right.
Getting an accurate Mississippi quote
The path to a real number is to describe your real operation. Tell a broker your crew payroll and the work it covers, your revenue and the kind of roofs you leave behind, your license status, your work footprint across coast and interior, your trucks and equipment values, your storm-season claims history, and the limits your contracts require — including the umbrella your larger contracts may push you toward. From there a carrier with genuine roofing appetite can price it. The full coverage overview shows how each line fits together. When you are ready, start a quote and tell us how your crews work, or see the Mississippi roofing contractor insurance page for the market picture behind these drivers. The number at the end will reflect your business, which is the only number worth having.