

In our experience placing roofing contractors nationwide, including in Arizona, general liability insurance for a small roofing company of one or two people usually comes in around $1,000 to $1,500 for the year, and general liability with workers’ compensation for a larger roofing business usually comes in around $2,500 to $3,800 for the year. An Arizona roofer’s own quote can land inside or outside those ranges, and the drivers below are what move it.
Roofing contractor insurance in Arizona has no fixed price, and the sun, not a storm calendar, sets the tone. Constant ultraviolet exposure and heat wear down roofing materials all year, so whatever your crew installs in Arizona has to hold up in the sun long after the job closes. The figure is worked up from how your own company operates, not from a published table.
That answer frustrates owners who want an exact number, but it is the honest one, and the Arizona drivers are specific enough that understanding them is worth far more than any average. A residential re-roof crew in Phoenix and a commercial low-slope operation in Tucson are the same trade only in name. Below is what moves the number, starting with the exposure that defines Arizona roofing.
UV and heat, not storm season, lead the Arizona picture
Arizona roofs face intense year-round UV and heat degradation, plus North American Monsoon microbursts and haboob dust-storm wind, with occasional hail at higher elevations. For a roofing contractor the sun is the lead story because it works slowly and constantly — it ages materials, tests seams and fasteners, and lengthens the tail on the roofs you leave behind. Monsoon wind adds a sharper seasonal loss element on top. Both shape cost through the exposure on your completed work and through your loss record, which a carrier reads closely. For the full market and regulatory picture, see our Arizona roofing contractor insurance page — that page is the overview, and this one is the cost explainer that companions it. The market is overseen by the Arizona Department of Insurance and Financial Institutions. For residential shingle crews in the Phoenix area, see workers’ comp for shingle roofers in Phoenix.
Why there is no fixed price
A premium is the result of an underwriting calculation rather than a posted price. Your premium is built from headcount and the tasks those people perform up on the roof, the revenue tied to finished work, past losses, and the limits your customer contracts call for, and each line is priced from those inputs. Alter one input and the result shifts. Averages across the state tell you little, since a re-roofer focused on homes and a contractor doing flat commercial roofs present quite different risks. Two things build a roofer’s cost: crews working high above the ground and the roofs left standing afterward in strong sun. In Arizona, heat makes durable workmanship that meets current code worth documenting. Installed roofs face a long stretch of UV-driven aging, so inspection records and callback history belong in your submission, and that proof can matter more than an advertised rate.
The ROC roofing license and your classification
Arizona is a state that actually licenses roofing. The Registrar of Contractors requires a roofing license for work valued above the state threshold, as a specialty classification with residential, commercial, and dual residential-commercial forms. A carrier reads that licensed, classified operation as a real business rather than an unknown, and the form you hold signals the work you do. A residential-only operation and a dual residential-commercial one carry different exposures, so matching your license form to your actual work mix is part of presenting an accurate picture, not a line item on a rate.
Crew payroll and the work at height in extreme heat
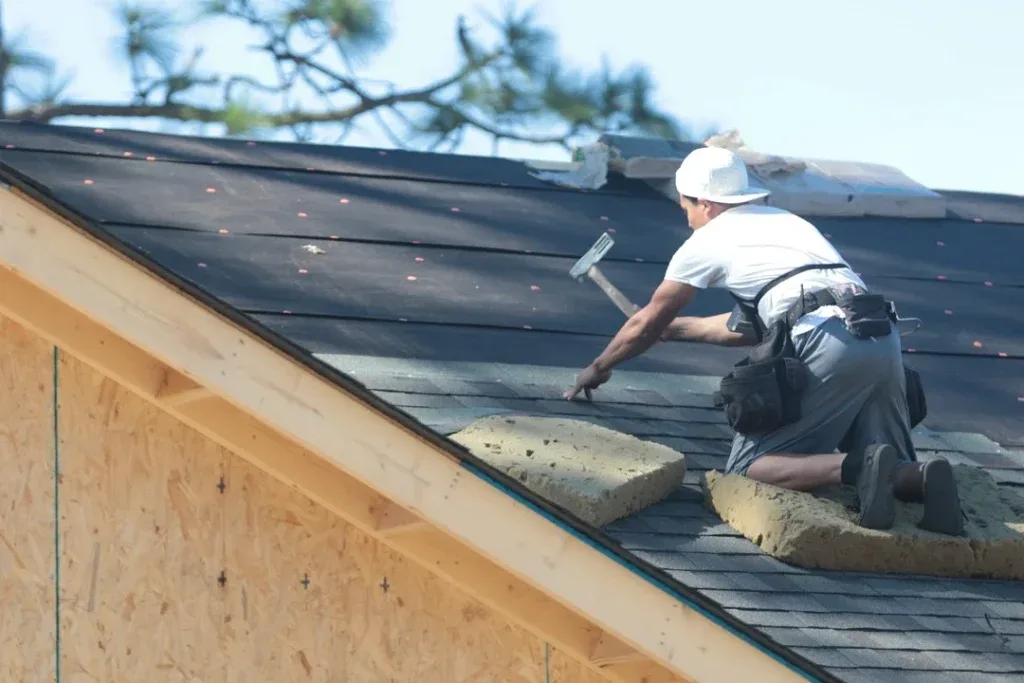
For a roofing contractor, payroll sets the base for your workers compensation and for part of your general liability, so it carries weight in the price. The amount matters, but so does the type of work behind it. Roofing crews work at height, and a crew member’s fall is a workers compensation claim, which is the loss this coverage exists to absorb. The Occupational Safety and Health Administration makes fall protection the centerpiece of roofing safety for that reason. Arizona adds extreme heat, and heat stress stacks onto fall risk, so tell us how your crews handle both, not only your headcount.
The completed-operations tail under relentless sun
Your revenue is a rating basis for general liability, but for a roofing contractor the exposure that defines the class is completed operations — the work you leave behind. A roof keeps existing after your crew is gone, and in Arizona that installed roof is baked by year-round UV that ages materials and tests workmanship over time. A roof that leaks or fails downstream can become a serious third-party property-damage or injury claim long after the job closes, and the completed-operations side of general liability is the signature line built to answer for it. Because relentless sun stretches the tail on an Arizona roof, your revenue and your workmanship-and-inspection record are inputs a carrier weighs closely. This is the roofing contractor’s defining cost driver.
Real-World Scenario: A Phoenix residential crew re-roofs sun-worn homes through a monsoon repair season, its trucks and payroll surging with demand, while a Tucson commercial contractor runs low-slope work on larger flat-roof projects that must reflect and shed heat for years. Both leave finished roofs judged against relentless UV, but an underwriter reads them differently — the residential crew’s exposure rides fall risk in extreme heat across many pitched roofs, the commercial contractor’s on fewer, larger low-slope jobs and higher contract limits. Same Arizona, same roofing class — but the work mix and the completed-work picture price differently. The owner who can describe that picture clearly gets a sharper quote.
Work type, the hot-work share, and coverage
Your mix of roofing work and your volume both shift the price. A residential crew on pitched roofs is rated on fall exposure and the completed work left behind. A commercial low-slope contractor adds fire risk from torch application and other hot work while the job is underway, plus higher limits and additional-insured demands on bigger contracts. A specialty metal and tile installer handles costly materials and has little room for installation errors. Arizona heat and UV bear on each of these categories, but hot work on torch-applied membranes is a risk during construction only; the sun-aged completed work afterward is a separate matter. Tell us what share of your revenue comes from torch-applied systems versus mechanically attached ones, so the quote reflects your real operation and nothing is left to guesswork.
The last driver is the program you choose to buy. Requirements written into contracts with general contractors, developers and project owners can make an umbrella worth considering, and bigger limits carry a bigger price. That matters in roofing, where one failed installation or one hot-work fire can exceed a primary limit. Also consider whether your general liability carries a products-completed-operations aggregate sized to your revenue, whether your equipment is scheduled at true value, and how each limit is set. Buying deliberately in these areas, rather than under-buying to save money, separates a bargain policy from the correct one.
Trucks, equipment, coverage, and an accurate quote
Two more things get priced beyond the crew and the finished roofs: vehicles and owned gear. Commercial auto responds for the trucks and trailers that carry crews, debris and material around Phoenix, Tucson and the long drives between jobs, and the bill climbs with fleet size. Contractors’ equipment, written as inland marine, protects tools, harnesses and other fall-protection gear, forming machines, and materials staged on a site. Your larger contracts may call for an umbrella, so line up each coverage with the agreements you really sign. The coverage overview lays out how the lines work together. For an actual figure, lay out your true operation: payroll, revenue, license form, work mix, equipment values and loss record. Then begin a quote, or read the Arizona page on roofing contractor insurance for market context. The resulting figure will be yours alone, built from your own operation and no one else’s.