

In our experience placing roofing contractors nationwide, including in North Dakota, general liability insurance for a small roofing company of one or two people usually comes in around $1,000 to $1,500 for the year, and general liability with workers’ compensation for a larger roofing business usually comes in around $2,500 to $3,800 for the year. A North Dakota roofer’s own quote can land inside or outside those ranges, and the drivers below are what move it.
There is no fixed price for roofing contractor insurance in North Dakota, and the state’s monopolistic workers-compensation system is the first reason a carrier can’t simply hand you one. Comp here runs through a single state fund rather than a competitive market, so your cost is assembled from your operation — the crew working at height, the roofs you leave behind, and the northern-plains winter — never from a rate card.
That answer frustrates owners who want an exact number, but it is the honest one, and the North Dakota drivers are specific enough that understanding them is worth far more than any average. A residential shingle crew in Fargo and a low-slope commercial operation in Bismarck are the same trade only in name. Below is what moves the number, starting with the one structural fact that sets this state apart.
Workers comp runs through one door in North Dakota
North Dakota is one of a small handful of monopolistic workers-compensation states, which means the comp piece of your program has exactly one channel: the state fund, North Dakota Workforce Safety and Insurance. No private carrier writes workers compensation here, so there is no open-market comp quote to shop. That is unusual, and it changes how the cost conversation starts.
Roofing deserves particular attention within that state-fund arrangement: crews work up on roofs, and a fall is a workers compensation claim, the injury this line exists to cover. The Occupational Safety and Health Administration builds its roofing safety approach around fall protection for the same reason, and your safety habits belong in the submission for your comp. Everything outside the state fund, the lines written by private carriers, is placed separately, and the North Dakota Insurance Department supervises that private market. Total cost therefore flows from two channels operating together instead of one. For the wider market and regulatory background, read our North Dakota roofing contractor insurance page; it serves as the overview, while this guide is the cost explainer that accompanies it.
Why there is no fixed price
Start with the workers compensation side: in North Dakota that coverage comes only from the state fund, so it is priced separately from everything a private carrier writes. For those private lines, premium is the product of an underwriting model and not a posted price. Headcount and the tasks done on the roof, revenue tied to finished jobs, loss history, and the limits your contracts impose all go into the price of each line. Move an input and the figure moves. The state has no statewide roofing or general-contractor license, with requirements set locally, so the shape of your operation matters, not a credential. In short, a roofer’s price is built from crews working high and the roofs left standing.
Crew payroll and the work at height
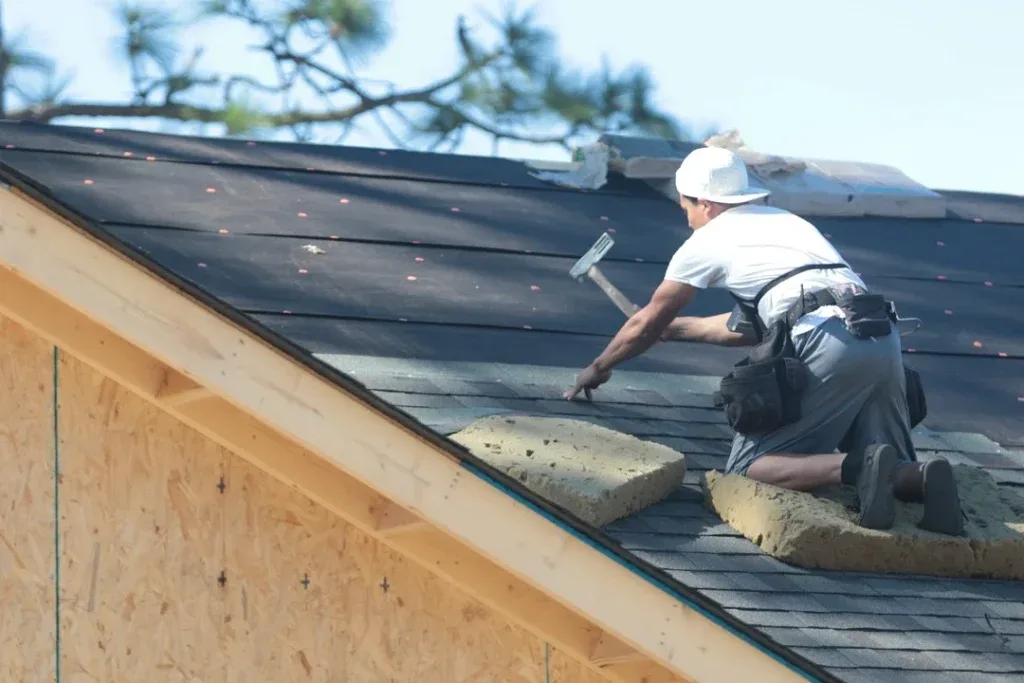
Payroll is usually the single biggest driver for a roofing contractor, because it scales both the comp priced through the state fund and a large part of your general liability. It is not just the dollar figure — it is which work the payroll covers. Roofing is among the highest-severity classes of any trade because the crew works at height, so a carrier and the fund alike read your crew’s fall-protection discipline as closely as its size. Training records, tie-off practice, and a clean injury history are not paperwork; they are what a well-run North Dakota roofing operation shows to earn accurate pricing rather than a cautious one.
The roof you leave behind — completed operations
General liability rates on revenue, but completed operations is what really characterizes roofing: the work that remains once your crew has gone. An installed roof stays in service, and if it leaks or fails later, a third party can bring an injury or property-damage claim long after the job is closed. Completed operations under general liability is the part built to respond. Because that tail lasts so long, your revenue and your workmanship and inspection record belong in the submission. In the northern plains, where heavy snow load and freeze-thaw stress are part of each winter, that record has to hold up season after season. A finished roof stays behind after the crew does.
Northern-plains snow load, ice dams, and your loss record
North Dakota’s winters do real work on roofs. Heavy snow loads, ice-dam formation, and freeze-thaw cycling stress roofing hard, while open-plains high wind and warm-season hail add seasonal damage. For a roofing contractor that shapes cost in two ways. It drives demand, so a hard-winter recovery season can push revenue up and then settle, and a carrier reads the revenue behind that work. And it concentrates loss activity into seasons, so your claims history — how your installed roofs and your crews held up through the worst of it — is a driver a carrier weighs closely.
Real-World Scenario: A Fargo residential crew works through a snow-load and ice-dam winter, its trucks and payroll surging with spring repair and re-roof demand, while a Bismarck commercial contractor keeps a low-slope crew on larger flat-roof projects across the season. Both leave finished roofs that must perform through the next freeze-thaw cycle, but an underwriter reads them differently — the residential crew’s exposure rides fall risk across many pitched roofs and storm-driven volume, the commercial contractor’s on fewer, larger low-slope jobs and higher contract limits. Same monopolistic-comp state, same roofing class — but the work mix and the completed-work picture price differently. The owner who can describe that picture clearly gets a sharper quote.
Work type, slope, and the hot-work share
The type of roofing you perform shifts the price along with volume, and in North Dakota the line between steep-slope and low-slope work sits alongside the state-fund comp arrangement your crew shares. Take a residential steep-slope contractor first: the profile is fall exposure plus completed operations, shaped by pitched shingle work at height and by repair volume after a hard season. A commercial and industrial low-slope operation is priced differently, since torch-down and other hot-work methods can create a fire hazard during the job, apart from the completed-operations tail that comes later, and larger contracts can carry additional-insured wording and higher limits. An installer of specialty metal and tile faces costly materials and the risk of imprecise installation. One trade produces three separate pricing discussions, so we ask about your mix before we quote. On the low-slope side, hot work belongs in the submission, because a torch or kettle creates fire risk as soon as work begins in cold weather. On the steep-slope side, standing-seam metal suits the heavy snow of the northern plains. Tell us plainly what share of your revenue is torch-down and what share is mechanically fastened, and how much is steep-slope compared with flat; an accurate quote depends on those answers, not on guesses.
Trucks, tools, and staged materials
The vehicles you drive and the gear you own are priced too. Commercial auto responds for trucks and trailers that move crews, tear-off debris, and materials, and the cost scales with your fleet. Contractors’ equipment, an inland marine coverage, pays for tools, harnesses and other fall-protection gear, standing-seam and metal-forming machines, and materials staged on the jobsite or moving through a long winter. Trucks and equipment also enter the price, and you control them: schedule trucks and equipment at real value instead of guessing. Listing them accurately is cheap compared with discovering a gap after a loss.
Getting an accurate North Dakota quote
The path to a real number is to describe your real operation. Tell a broker your crew payroll and the work it covers, your revenue and the kind of roofs you leave behind, your work mix across steep-slope and low-slope and specialty, your trucks and equipment values, your claims history through the northern-plains seasons, and the limits your contracts require. From there the private-market lines can be marketed to carriers with genuine roofing appetite while the comp piece is set through the state fund, and you can see how the whole program fits. The full coverage overview shows how each line — including the umbrella your larger contracts may require and the residential roofing work that drives your winter-recovery volume — works together. When you are ready, start a quote and tell us how your crews work. The number at the end will reflect your business, which is the only number worth having.