

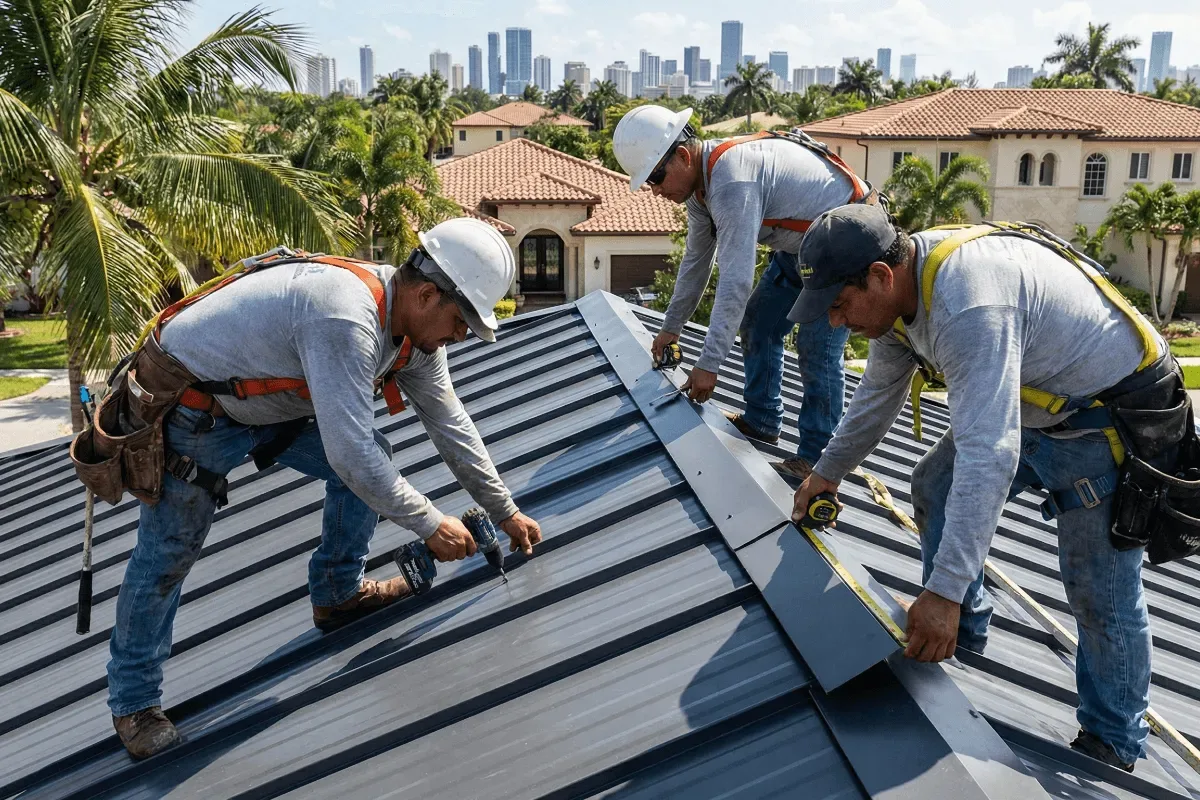
In our experience placing roofing contractors nationwide, including in Missouri, general liability insurance for a small roofing company of one or two people usually comes in around $1,000 to $1,500 for the year, and general liability with workers’ compensation for a larger roofing business usually comes in around $2,500 to $3,800 for the year. A Missouri roofer’s own quote can land inside or outside those ranges, and the drivers below are what move it.
There is no fixed price for roofing contractor insurance in Missouri, and two features of the state explain most of why not. The first is on the map: Missouri credentials roofers city by city rather than statewide, and its two big metros — St. Louis and Kansas City — each run their own contractor regime, so where you are based already changes the paperwork behind your bids. The second is in the weather: Missouri sits on the eastern edge of Tornado Alley, and a storm belt that severe writes your claims record into your price more heavily than a calmer state ever would. A carrier assembles the cost from your specific operation, and this guide walks the drivers that decide what a Missouri roofing contractor pays.
A range frustrates owners who want an exact figure up front, but it is the honest one, and Missouri’s mix of local licensing and storm weather makes the drivers worth understanding. A residential shingle crew and a low-slope commercial operation are one trade in name only, and each needs its own picture in your submission. Here is what moves the number for a Missouri roofer, roughly in order, and what you can influence. For the wider picture, see our overview of roofing contractor insurance.
Why Missouri publishes no roofing insurance price
A premium is the product of underwriting, not a price list. The carrier gathers your true exposures — headcount and what the crew does aloft, the revenue behind your completed work, your loss record, and the limits your contracts set — and rates each line against them, so any change to the inputs changes the total. Missouri makes a statewide average especially hollow for two reasons pulling in different directions. On the regulatory side there is no state roofing license at all; credentialing is municipal, and St. Louis and Kansas City lead it with distinct rules that shift from one city to the next. On the loss side the geography is severe and uneven: the eastern reach of Tornado Alley, frequent hail and damaging wind statewide, and winter freeze-thaw in the north. Where you are licensed and where your roofs take their weather can diverge sharply, and a carrier reads both. The Missouri roofing contractor insurance page carries that fuller picture; this page stays on cost. For the workers’ comp side, from Kansas City and St. Louis to the Lake of the Ozarks, see workers’ comp for roofers in Missouri.
The two-metro credential picture
Because Missouri hands roofing oversight to its cities, the two metros anchor the credential map, and they do not run identical playbooks. A contractor licensed under the St. Louis regime and one working out of Kansas City can face different registration, bonding, and permit expectations, and a roofer who crosses between the metros and the smaller markets in between carries the widest paperwork of all. None of that is a line on your premium by itself, but it shapes the contracts you sign and the certificate-of-insurance terms those contracts demand — which limits, which additional insureds — and those choices are exactly what a carrier prices. Getting the credential-and-contract picture straight for the markets you actually work is the groundwork under an accurate Missouri quote. The split can even reshape your profile as you grow: a Kansas City operation that starts working both sides of its market area picks up one more layer of local expectation, and the contracts that come with the expansion carry their own coverage terms into your program.
Payroll and the class the crew rates into
For nearly every roofer, payroll is the heaviest single driver, because it powers both your workers compensation and a wide band of your general liability. The figure alone does not tell the story — the class the payroll falls under does. Roofing ranks near the top of the severity scale among all trades for a reason nobody can argue with: the work is done at height, and the claims comp exists to pay are the ones a fall creates. The Occupational Safety and Health Administration anchors its roofing standards on fall protection on exactly that logic, and a carrier weighs your crew’s safety habits as seriously as its size. Missouri runs a private comp market regulated by the Missouri Department of Commerce and Insurance, so competing carriers set that class against your record — and matching the class honestly to the work is part of pricing the driver, not an add-on.
The completed-operations tail — the work that stays behind
Roofing earns its own pricing logic from a single fact: the job outlives the crew. When your people drive away, the roof remains on the structure, and a roof that leaks or fails somewhere down the road can become a third-party property or injury claim long after the account was paid. The completed-operations half of general liability is the coverage built to stand behind that, and because an installed roof trails such a long tail, a carrier reads your revenue and your workmanship-and-inspection history closely as it prices the line. This is the driver that separates roofing from trades that clear the site clean at day’s end — for a Missouri contractor, the roofs already delivered keep influencing the next renewal.
The kind of roofing you do
Your work mix bends the number as much as your volume does. A residential steep-slope crew carries the fall-and-completed-work profile of pitched shingle work driven by storm cycles. A commercial and industrial low-slope crew brings torch-down and other hot-work methods that concentrate a genuine fire exposure on the job, plus the additional-insured and higher-limit demands that ride with larger contracts. A specialty metal and tile installer carries steep material values and precision-install risk. One class code, three genuinely different conversations — and a carrier wants the mix before it prices.
The claims ledger — how your record prices Missouri
In a state this storm-prone, your loss history does more work than almost anywhere else. Missouri parks on the eastern edge of Tornado Alley, where tornadic and straight-line wind and frequent hail crush roof losses into intense seasons — the Joplin tornado is the extreme reminder of what the geography can do — and the north adds freeze-thaw and ice loading on top. That severity feeds cost along two paths. It surges demand, so revenue can leap in a heavy season and then subside, and a carrier watches the revenue behind that swing. And it concentrates claims into narrow windows, which turns your record — how your crews and your workmanship held up when a hailstorm filled the schedule — into a driver a carrier studies line by line. A clean ledger through a brutal Missouri season is worth more here than a clean ledger in a placid climate, because it proves the operation performs under exactly the stress the state guarantees.
Depth of record matters as much as its cleanliness. A carrier sizing up a Missouri roofer wants more than one quiet year; it wants to see how the operation handled the seasons that actually tested it, because a calm twelve months proves little in this climate. An owner who can show steady workmanship and a controlled loss pattern across several severe springs offers the kind of evidence that moves a rate, while a thin or recent history leaves the carrier pricing the uncertainty instead.
Real-World Scenario: A Kansas City crew rides a spring stacked with tornado watches and hail, growing its trucks and payroll to keep up with re-roof orders, while a St. Louis contractor spends the year torching down low-slope decks on a handful of larger buildings. Both leave finished roofs that have to perform for years, yet an underwriter reads two different ledgers: the Kansas City crew’s risk rides storm-driven volume and falls across many pitched roofs, the St. Louis contractor’s rides hot-work fire and fewer, larger jobs. Same Missouri, same class code — different records, different price. The owner who can walk a carrier through that record earns a sharper quote than the one who cannot.
The trucks and gear behind the crew
Beyond people and completed work, a carrier prices your rolling stock and your kit. Commercial auto answers for the trucks and trailers that haul crews, tear-off, and material, and it scales with the fleet. Contractors’ equipment — inland marine — covers the tools, harnesses and fall gear, seaming and forming machines, and the material staged on-site and in transit. For a roofer these usually rank behind the crew and the completed-work tail, but they reward accuracy: schedule everything to genuine replacement value and you neither overpay nor leave the gear that moves crews to a finished roof underinsured.
Coverage limits, and getting an accurate Missouri quote
What you buy is the last driver. The limits your general contractors and project owners require push you toward an umbrella, and because a single completed-work failure or hot-work fire can run past a primary limit, higher limits cost more for the plain reason that they answer for more. Carrying the products-completed-operations aggregate your revenue actually calls for is a deliberate decision rather than a default, and the coverage overview shows how the lines interlock. When you want a real number, lay the whole operation out for a broker — crew payroll and its work, revenue and the roofs you leave behind, your mix across steep-slope, low-slope, and specialty, your equipment values, your claims ledger, the limits your contracts require, and where in Missouri you work. From there a carrier with real roofing appetite can price it and you can compare like with like. Start a quote when you are ready, or read the Missouri roofing contractor insurance page for the market and regulatory context behind these drivers.